

Best Startup Business Loans for 2026
The best startup business loans for 2026 are SBA microloans, SBA 7(a) loans from lenders that finance new businesses, nonprofit and CDFI loans, and equipment leases, with platform and revenue-based financing joining the list once you have a few months of sales. A business with no revenue yet borrows on the owner's credit, cash and plan, so expect small first loans and a personal guarantee. Below are nine named options, the stage each one fits, and what you'll actually sign.
The short version: Before revenue, start with an SBA microlender or a nonprofit lender and put your own cash in. If you're buying equipment, lease or finance it so the equipment carries the deal. Once deposits arrive, platform and cash-flow lenders open up. Plan on a personal guarantee; for an SBA 7(a) loan, every owner of 20% or more must sign one.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Funding in as little as 24 hours
Best startup business loans at a glance
Startup money rarely comes from one place, so this list mixes government programs, nonprofit lenders, an equipment lessor, a bank and online lenders. Requirements change, and each company publishes its own on the pages we link below.
| Option | Best for | Stage it fits | How you apply |
|---|---|---|---|
| SBA microloan | A small first loan from a community lender | Pre-revenue to early | Through an SBA intermediary lender |
| SBA 7(a) via Lender Match | Larger launches and buying a business | Solid plan and owner cash in the deal | SBA's Lender Match tool, then the lender |
| Accion Opportunity Fund | A nonprofit lender with free advising | Early; varies by product | Online application |
| Clicklease | Small equipment purchases | Startups with limited time in business | Through a partner equipment seller |
| Bank of America Cash Secured Line | Starting a bank credit record | Early, with cash to pledge | Bank of America |
| Fundbox | A credit line on a short bank history | A few months of checking activity | Online, soft pull to apply |
| Shopify Capital | Shopify stores | After a short selling history on Shopify | Offer and application in your Shopify admin |
| Lighter Capital | SaaS with recurring revenue | Post-revenue software companies | Online |
| Quordx | Comparing lenders once deposits are steady | Operating, with regular deposits | One online application |
How we chose these startup loan options
Every option was checked on its own website in October 2026. Each one had to show a real path for a young business: its pages say it serves startups or businesses starting up, or it judges eligibility on something a new business can have, like platform sales, recurring revenue or the equipment being bought, instead of years in business.
We left off lenders whose published time-in-business requirements a startup can't meet yet, and merchant cash advances, which take daily debits a business without steady sales can't carry. Business credit cards get a short note below rather than a slot on the list.
Quordx publishes this page and is paid by lenders when a deal funds. It appears last, because for a pre-revenue business the other eight are the better first stop.
Run the numbers on your loan
Pick a product, set the amount and term, and see a typical payment.
The 9 best startup business loan options
1. SBA microloan: best for a small first loan
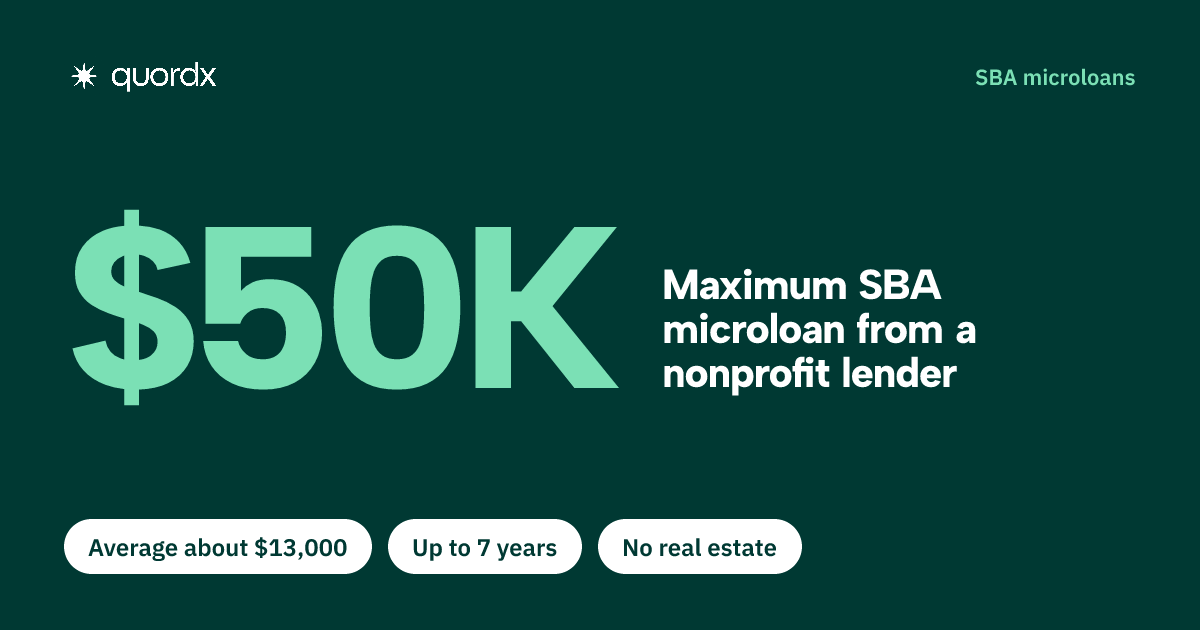
SBA funds nonprofit, community-based intermediary lenders, which relend to businesses that need less than $50,000 to start or grow. SBA's own figures: loans up to $50,000, an average of about $13,000, a maximum term of seven years, and rates that vary by lender but generally fall between 8% and 13%.
Uses: working capital, inventory, supplies, furniture, fixtures, machinery and equipment. Not allowed: paying off existing debt or buying real estate.
The catch: the intermediary makes every credit decision and sets the terms, including collateral and guarantee rules, so two microlenders can answer differently. Find one through SBA's list of microlenders, and read our explainer on what an SBA microloan is.
2. SBA 7(a) through Lender Match: best for larger launches and acquisitions
7(a) is SBA's main loan program, with a maximum of $5 million. SBA's lender guide lists starting a business and changes of ownership among eligible uses, while its borrower page requires an operating business, so the lender's read of your plan decides. Lender Match prepares a list of interested lenders two business days after you submit a request; it isn't a loan application and doesn't guarantee a match.
The ceiling is public: SBA caps variable rates by loan size, from base rate plus 6.5 points up to $50,000 down to plus 3 points above $350,000. With prime at 7.00% as of October 2026, that's a maximum of 13.50% on the smallest loans and 10.00% on the largest.
The catch: every owner of 20% or more signs an unlimited personal guarantee. SBA also tightened its ownership rule effective March 1, 2026, requiring all owners to be U.S. citizens or U.S. nationals living in the U.S., so confirm the current rule with your lender.
3. Accion Opportunity Fund: best for a nonprofit lender with advising
Accion Opportunity Fund is a 501(c)(3) nonprofit that pairs loans with free business advising. Its menu covers term loans, SBA 7(a) loans, equipment leasing, truck financing and food truck financing, and its truck and food truck programs speak directly to owners launching a business.
Why it's here: it describes its mission as serving owners who have historically lacked access to affordable financing. The catch: its loans page doesn't publish eligibility rules, and it doesn't lend in DC, Montana, North Dakota, South Dakota, Tennessee or Vermont.
4. Clicklease: best for small equipment purchases
Clicklease leases equipment through partner sellers and pays the seller directly. Its FAQ names start-ups with limited time in business and customers with poor credit among those it approves, and a bank verification step can avoid a hard credit pull.
How the cost works: because it's a lease, Clicklease charges a fixed surcharge spread across the payments instead of interest, and every lease includes an option to buy the equipment at the end. The catch: it publishes a cap that suits smaller purchases, and lease costs are easy to underestimate, so add every payment plus the buyout and compare that to the cash price.
5. Bank of America Cash Secured Line of Credit: best for starting a bank credit record
Bank of America's cash secured line of credit is backed by a deposit you put up, and the bank lists its time-in-business and revenue requirements on the same page. It pitches the line as a way to build credit and says you can graduate to an unsecured line over time.
Why it's here: the bank's unsecured line and term loan have longer time-in-business requirements, so this is the on-ramp to them. The catch: you're borrowing against your own cash, which builds a record but adds no new capital.
6. Fundbox: best for a credit line on a short bank history
Fundbox makes lines of credit and loans available through First Electronic Bank or Lead Bank. Its FAQ lists one requirement: a business checking account with a minimum history of transactions.
Why it's here: it measures account activity rather than your incorporation date. The catch: the application uses a soft pull, but Fundbox runs a hard pull at your first draw if you're approved, and eligibility follows each partner bank's own credit policies.
7. Shopify Capital: best for Shopify stores
Shopify Capital loans are issued by WebBank in the U.S. and repaid as a fixed percentage of daily sales, collected only on days you sell. Shopify says there are no credit checks and no impact on your personal score, and it publishes a minimum selling history on Shopify.
Why it's here: a young online store has little to show a bank, but it has sales data, and Shopify underwrites on that. The catch: it's for Shopify merchants only, eligibility comes from Shopify's model plus a team review, and a percentage of sales is easy to accept and hard to price, so ask for the total repaid.
8. Lighter Capital: best for SaaS companies with recurring revenue
Lighter Capital provides non-dilutive financing to technology and SaaS companies with steady recurring revenue, and says it takes no equity, board seats or personal guarantees.
Why it's here: it's the rare option on this page that doesn't ask the founder to back the debt personally. The catch: its published criteria cover recurring revenue, paying customers, revenue model and location, so a pre-revenue software company isn't a fit yet.
9. Quordx: best once your deposits are steady
Quordx doesn't lend; it brokers. One application, about 10 minutes, goes to lenders in a network of 50+, and it's free to you because lenders pay Quordx when a deal funds. Those lenders typically decide in 24 to 48 hours. See how the marketplace works.
The honest fit: lenders need something to underwrite, and a business with no deposits gives a cash-flow lender little to read. Before revenue, options 1 through 8 will serve you better; come back once deposits are coming in. Businesses in Virginia, Connecticut, Missouri and North Dakota are outside the states Quordx serves.
Which startup loan fits your stage
- No revenue, small need: an SBA microlender or a nonprofit lender, plus your own cash. Take the advising if it's offered.
- No revenue, big need (a build-out, franchise or acquisition): SBA 7(a) through Lender Match, with a full plan, projections and owner money in the deal.
- You need equipment: lease or finance it so the equipment secures it. See equipment financing for a new business.
- You sell on Shopify or Square: check your dashboard for an offer before applying anywhere else.
- Software with subscription revenue: look at Lighter Capital and other revenue-based lenders.
- A few months of steady deposits: add Fundbox, and compare lenders through a broker once you have a track record. Our guide on whether a startup can get a business line of credit covers that step.
- No urgent need yet: open a cash-secured line now so you have a payment record when you do need to borrow.
What startup loans cost: two worked examples
A $25,000 SBA microloan
Say an intermediary lends $25,000 at 10% over six years. The 10% is an assumption that sits inside SBA's stated 8% to 13% range; your lender sets the real rate.
- Monthly payment: about $463.
- Total interest over 72 payments: about $8,347.
A $150,000 SBA 7(a) startup loan
Say a lender approves $150,000 at SBA's maximum variable rate for that loan size, prime plus 6 points, which is 13.00% with prime at 7.00% as of October 2026. Assume a 10-year term.
- Monthly payment at the ceiling: about $2,240.
- SBA guaranty: up to 85% on loans of $150,000 or less, so $127,500.
- Upfront guaranty fee: 2% of the guaranteed portion for loans approved in fiscal 2027, so $2,550.
- Lender's annual service fee: 0.55% of the guaranteed balance, which the lender may not pass on to you.
Decision rule: make the payment work on your slow-month projection, not your best case. If $2,240 a month only works when every forecast hits, borrow less or put in more of your own cash.
Personal guarantees: what startup founders actually sign
A personal guarantee makes you personally liable if the business can't pay. Forming an LLC or corporation doesn't change that, because the guarantee is a separate promise you sign as an individual.
SBA's rule is written down: On SBA Form 148, SBA states that individuals who own 20% or more must provide an unlimited personal guaranty. Owners under 20% may give a limited or full guarantee.
It's the norm well beyond SBA: In the Federal Reserve's 2025 survey, 59% of small employer firms with debt had used a personal guarantee to secure it. For a startup with no operating history, expect to be in that group.
What to ask: whether the guarantee can be capped at a dollar amount, whether minority owners can sign a limited version, and whether it ends once the loan is paid down. Lighter Capital is the exception on this list that says it takes no personal guarantee. More detail: do small business loans require a personal guarantee?
Business credit cards for startups: where they fit
Many founders put early costs on a business credit card. For a brand-new company, the issuer leans on the owner's personal credit, and small business cards typically come with a personal guarantee.
Use a card for short gaps you can clear, not as the launch loan: Carrying a balance month after month is an expensive way to fund a startup, and stacking several cards to raise capital makes the problem harder to unwind.
What lenders look at when your business is new
With no operating history, the lender underwrites you. Your personal credit report, the cash you're putting in, your experience in the industry and the plan itself carry the decision. Collateral, such as equipment or real estate, can make up for a thin file.
Mistakes that sink first applications: running business money through a personal account, which leaves no business statements to read; borrowing the whole budget with nothing in reserve; and taking a merchant cash advance before sales are steady. For more on the full funding mix, including grants and equity, see how to fund a startup business.
Questions Business Owners Ask Before Applying
Can I get a startup business loan with no revenue?
Yes, in smaller amounts and from specific lenders. SBA microlenders, nonprofit lenders and some SBA 7(a) lenders will review a pre-revenue business on the owner's credit, cash and plan, and equipment can be leased against its own value. Cash-flow lenders need deposits to read, so they come later.
Do SBA loans finance startups?
Some do. SBA's microloan page says the program helps businesses start up and expand, and its 7(a) lender guide lists starting a business as an eligible use. The lender still has to be satisfied you can repay, so a full plan and owner cash in the deal matter.
What credit score do I need for a startup business loan?
There's no single number, and each lender sets its own. With no business history, your personal credit carries more of the decision than it would for an established company. Our page on SBA loan credit score requirements covers the SBA side.
Can I get a startup loan without a personal guarantee?
It's uncommon. SBA requires an unlimited guarantee from every owner of 20% or more, and in the Fed's 2025 survey most small firms with debt had used one. Lighter Capital says it takes none, but it lends to software companies that already have recurring revenue.
How much can a startup borrow?
It depends on the program and on what backs the loan. SBA microloans top out at $50,000 and 7(a) loans at $5 million, but a first loan is usually sized to the owner's cash, credit and collateral rather than the program maximum. Size the request to the payment your slow months can carry.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources

Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures