

Small business loans with EIN only: what's actually possible
Small business loans with EIN only, meaning no personal credit check and no personal guarantee, are rare for most small businesses. Most lenders still check the owner's personal credit and ask for a personal guarantee, even when you apply under the business's EIN. An EIN-only file can work in a few situations: an established business with real credit files at Dun & Bradstreet, Experian Business and Equifax Business plus strong financials, receivables-based products, some equipment deals, and corporate cards underwritten on the company's bank balance. Everyone else can build toward it, and the steps are below.
The short version: Your EIN identifies the business. It does not replace you as the person a lender can collect from. If you need money in the next few months, expect a personal guarantee and plan for it. If you want to borrow on the business alone later, build reported trade credit, keep the business's money separate, and grow revenue and cash on hand, because those are what move a lender off your personal file.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Funding in as little as 24 hours
Why lenders still check your personal credit when you apply with an EIN
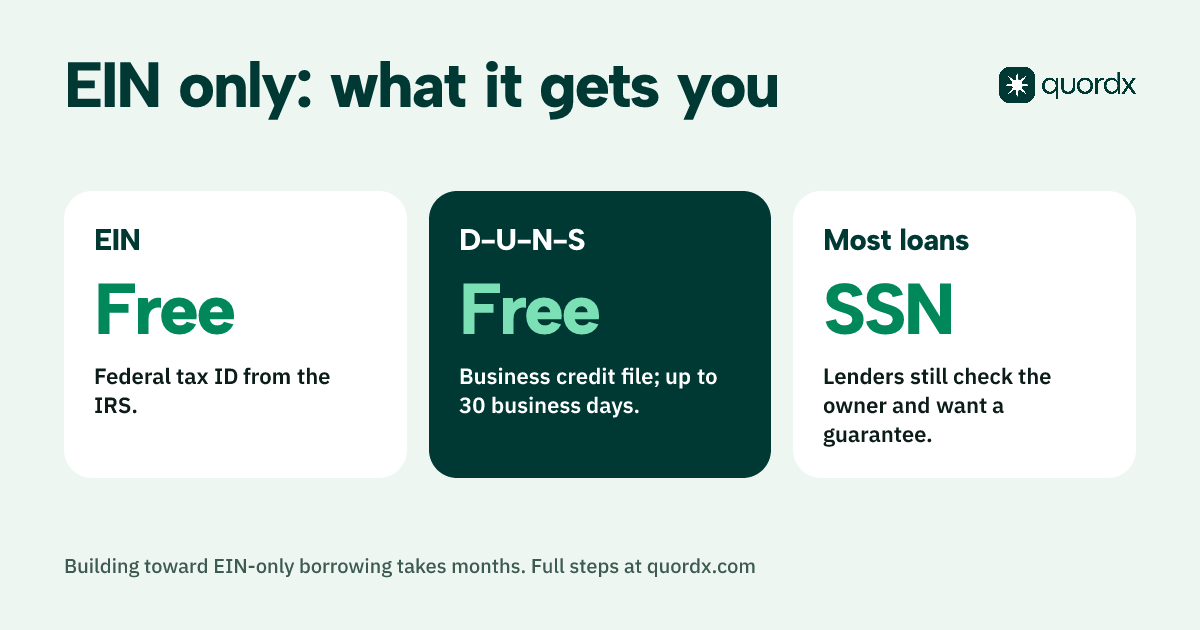
An EIN is a federal tax ID for the business, and the IRS issues one free. It tells a lender which entity is borrowing. It says nothing about whether that entity can repay.
The guarantee is the lender's backstop: A young or small business has a short record and few assets a lender can claim. A personal guarantee gives the lender a second source of repayment, and your personal credit tells it how that person handles debt. In the Federal Reserve's 2025 Small Business Credit Survey, 59% of firms with debt used a personal guarantee to secure it, while 51% used business assets.
Cards follow the same rule: Mainstream small-business credit cards from the big issuers ask for the owner's Social Security number and a personal guarantee. A sole proprietor usually enters the SSN in both the personal and the business fields, which is where some of the EIN-only confusion starts.
A guarantee is a signed promise to repay from your own assets if the business cannot. Read what a personal guarantee on a business loan means before you sign one, including whether it is limited to a set amount or covers the whole debt.
When an EIN-only business loan can actually work
In each of the cases below, something other than you stands behind the debt. That is the whole trick.
An established business credit file plus strong financials
The three main business credit bureaus are Dun & Bradstreet, Experian Business and Equifax Business. A company with years of on-time payments reported to them, solid revenue and real cash in the bank gives a lender a record to underwrite instead of the owner's. No lender publishes the point where it drops the guarantee. It is a credit decision made file by file, and a business still opening its first trade accounts should not expect it.
Receivables-based products
With invoice factoring or receivables financing, the money comes back when your customers pay their invoices. That moves the credit question toward your customers. A business that invoices creditworthy companies may find the owner's personal credit carries less weight, but read the agreement for any owner guarantee before you sign.
Some equipment financing
The equipment is collateral, so the lender can take it back and resell it. For an established business buying equipment with a strong resale market, some lenders will rely on the asset and the company's numbers. For a new business, or specialized equipment that is hard to resell, expect a guarantee.
Corporate cards underwritten on the company's bank balance
A small group of corporate charge cards approve on business financials with no personal guarantee and no personal credit check. They are paid in full each cycle, they expect a meaningful cash balance in a business bank account, and some exclude sole proprietors. They are a spending tool, not a loan.
| Option | What stands behind the debt | Owner guarantee | Fits a new business? |
|---|---|---|---|
| Bank or online term loan or line of credit | Business cash flow plus the owner | Expect one | Yes, with a guarantee |
| Invoice factoring or receivables financing | Your customers' payments | Depends on the agreement | Yes, if you invoice other businesses |
| Equipment financing | The equipment | Sometimes waived for established firms | Expect a guarantee |
| Corporate charge card | Your business bank balance | No | Only with real cash in the bank |
| Net-30 vendor account | The vendor's view of your business | No | Yes, and it is where most files start |
Estimate your funding
Answer a few questions about your business to see a likely range.
The EIN-only reality check: what most lists get wrong
Most 'EIN-only credit cards' are not credit cards: Many lists online are really net-30 vendor trade accounts: store credit with one supplier, usable only with that supplier, that reports your payments to business credit bureaus. They build a file. They do not fund payroll or inventory.
'No personal guarantee' is an outcome, not a feature: Issuers that approve some businesses without a guarantee still keep a guarantor section on the application for businesses that do not qualify on their own file. You earn a no-guarantee approval with your numbers. You are not entitled to it because the marketing said so.
Skipping the credit check is not the same as skipping liability: Some sales-based advances approve without a personal credit pull. Read the signature page anyway, because the contract may still ask the owner to guarantee something.
A fee before you see an offer is a warning sign: Paying someone to get you approved on your EIN alone buys nothing a lender is bound by. Lenders make the credit decision.
How to build toward EIN-only borrowing, step by step
This is slow work, measured in months and years. Do the steps in order, because each one feeds the next.
- Form a legal entity. An LLC or corporation with its own name, address and phone number. A sole proprietorship shares an identity with the owner, and some no-guarantee products exclude sole proprietors.
- Get your EIN and open a business bank account. Run every deposit and bill through it. That account is the first thing a lender reads.
- Get a free D-U-N-S number. Dun & Bradstreet says there is no cost to request one, and most arrive within 30 business days. Some vendors check your D&B file before they grant terms. More in what a DUNS number is.
- Open net-30 trade accounts that report. Uline approves on business name, contact details and EIN, and reports to D&B and Experian Business. Quill also reports to both, after a lag of several months. See how net-30 accounts work.
- Pay every account on or before the due date. Each on-time payment becomes a line in your file. One late payment shows up there too.
- Check all three business files. Make sure Dun & Bradstreet, Experian Business and Equifax Business show the same legal name, address and EIN, because a mismatch can split your history. Here is how to check your business credit for free.
- Borrow with a guarantee now and repay it on schedule. A loan or line that reports to the business bureaus adds the kind of history a future lender can underwrite.
- Grow revenue and cash on hand. A clean file with thin revenue still gets a guarantee request. The business has to be able to repay from its own cash flow.
- Ask about the guarantee at renewal. When a line comes up for renewal, ask whether the lender will remove the guarantee or cap it at a set amount. The answer may be no, and asking costs nothing.
For the full playbook, see how to build business credit and building business credit with an EIN.
Which path fits your business right now
If you need funding in the next 90 days and the business is under two years old: apply with a personal guarantee and compare offers on total cost. Spend your energy on the price, not on avoiding the signature.
If you invoice other businesses: price receivables financing first. It is the most realistic way to put your customers' credit ahead of your own.
If you are buying equipment that holds its value: ask each lender directly whether it will approve without a guarantee given your time in business and financials.
If you have years of reported trade history, steady revenue and cash in the bank: ask for business-only terms outright. A file like that is the one EIN-only lending is built for.
Where Quordx fits if you want to limit personal liability
Quordx is a broker, not a lender, and it cannot remove a lender's guarantee requirement. What it can do is send one application, about 10 minutes, to lenders in a network of 50+ and show you which offers lean hardest on the business, such as receivables or equipment-backed options. Most options can be explored without a hard credit pull.
It is free to the business owner; lenders pay Quordx when a deal funds. Lenders typically return decisions in 24 to 48 hours. Quordx does not serve businesses in Virginia, Connecticut, Missouri or North Dakota, and California applicants see a state notice first. For more on the no-guarantee side, see small business loans without a personal guarantee.
Questions Business Owners Ask Before Applying
Can I get a business loan with just my EIN and no SSN?
For most loans, no. Lenders and card issuers ask for the owner's SSN to check personal credit and to identify the guarantor. Net-30 vendor accounts and some corporate charge cards are the main exceptions, and neither one is a loan.
Does applying with my EIN keep the loan off my personal credit report?
Not necessarily. The lender may still pull your personal credit when you apply, which can show as an inquiry. Whether the account itself appears on your personal report depends on the lender's reporting policy, so ask before you sign.
How long does it take to build business credit to the point of EIN-only borrowing?
There is no fixed timeline, because no lender publishes the point where it drops the guarantee. A D-U-N-S number can take up to 30 business days and some trade accounts take months to start reporting, so expect many months before your file has history a lender can read. Revenue and cash on hand matter as much as the file.
Is a personal guarantee the same as putting up collateral?
No. Collateral is a specific asset pledged to the loan, such as equipment or receivables. A personal guarantee is your promise to repay from your own assets if the business cannot. A loan can have either one, both or neither.
Will my LLC protect me if I sign a personal guarantee?
Not for that debt. An LLC generally keeps business debts separate from your personal ones, but a personal guarantee is a separate promise in which you agree to be liable yourself. The guarantee is exactly the step that reaches past the LLC.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources

Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures