

Small Business Lenders Near Me: How to Find Local Options and Vet Them
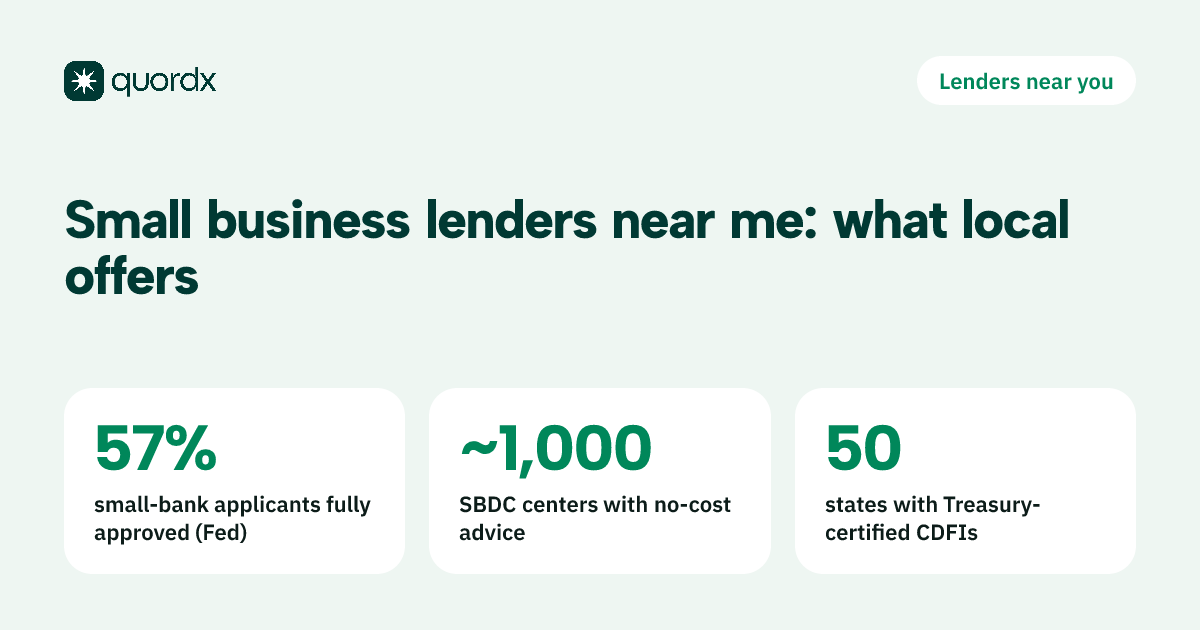
The small business lenders near you worth calling first are the bank that holds your business checking account, community banks and credit unions in your area, Treasury-certified CDFIs, and SBA-backed lenders you can find through SBA's free Lender Match tool. Free local help comes from your Small Business Development Center, SCORE mentors, Women's Business Centers and your SBA district office, none of which lend but all of which can point you to lenders that do. Local can pay off: in the Federal Reserve's 2025 Small Business Credit Survey, applicants at small banks were more likely to be fully approved (57%) than applicants at any other kind of lender (Federal Reserve Banks).
The short version: Start with the lender that already knows your deposits. If you need $50,000 or less, or your business is young, look for a CDFI or SBA microlender nearby. For an SBA loan, submit a Lender Match request and talk to the lenders that respond. Before you sign with anyone, local or online, confirm who they are and ask for the total cost in dollars.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Funding in as little as 24 hours
Types of small business lenders near you, and how to find each one
| Local option | How to find one near you | Good for | Watch for |
|---|---|---|---|
| Your current bank | Ask your branch or business banker | Owners with two or more years of deposits there | Firm minimums for time in business and credit |
| Community bank | FDIC BankFind lists insured banks by location | Relationship lending and local knowledge | May not offer SBA or equipment programs |
| Credit union | NCUA's credit union locator | Members who want lower costs | You must be eligible to join first |
| CDFI | The CDFI Fund's list of certified CDFIs, sortable by location | Newer, smaller or underserved businesses | Some serve only one city or county |
| SBA 7(a) or 504 lender | SBA Lender Match | Longer terms and larger amounts | More paperwork; SBA ownership rules apply |
| SBA microlender | SBA's list of microlenders by state | Loans up to $50,000 plus business advice | Small amounts only |
| SBDC, SCORE, Women's Business Center | SBA's local assistance search by ZIP code | Free help preparing the application | They advise; they do not lend |
| SBA district office | SBA's district office list by state | Training and pointers to local programs | Not a lender |
If you only make one call this week, make it to the bank that already sees your deposits. In the Fed survey, existing relationships were the main reason bank applicants chose their lender.
How to find SBA lenders and free help near you
SBA Lender Match: SBA does not lend directly under 7(a); approved lenders do. You describe what you need, and two business days after you submit, SBA prepares a summary of lenders interested in your request (SBA Lender Match). It is not a loan application and does not guarantee a match, and some lenders will reach out to you directly.
Small Business Development Centers: America's SBDC says its network has nearly 1,000 centers offering no-cost business consulting and low-cost training, hosted by universities, colleges, state agencies and private organizations (America's SBDC). An SBDC advisor can review your plan and projections before a lender sees them.
SCORE, Women's Business Centers and Veterans Business Outreach Centers: All three are SBA resource partners. SCORE mentors charge nothing, and a Women's Business Center's counseling is free or low cost (SBA resource partners). SBA's local assistance search finds them by ZIP code.
Your SBA district office: SBA lists district offices by state, and they offer business development services and training. Ask them about local programs, but do not expect a loan from them. For a comparison of SBA lenders, see best SBA lenders for small business.
Estimate your funding
Answer a few questions about your business to see a likely range.
Credit unions and CDFIs: the local lenders owners overlook
Credit unions: are member-owned, not-for-profit institutions, and their members share a common bond, such as an employer, a family tie, a group or where they live (MyCreditUnion.gov). Credit unions lend to their members, so check whether you can join before you ask about a business loan. NCUA's credit union locator shows which ones are near you.
CDFIs: are lenders certified by the U.S. Treasury's CDFI Fund that primarily serve low-income and underserved markets. They include community development banks, credit unions, loan funds and venture capital funds, and there are certified CDFIs in all 50 states, plus D.C., Guam and Puerto Rico (CDFI Fund).
How to find a CDFI near you: The CDFI Fund publishes its list of certified CDFIs, which you can sort by name, location or type, with contact details for each (CDFI Fund FAQ). Its award database lets you pick your state and narrow to CDFI Program awardees. If none are nearby, look at neighboring areas, because some CDFIs cover a single city and others a whole state.
SBA microlenders: are nonprofit intermediaries that make loans up to $50,000, averaging about $13,000, and they set their own terms (SBA microloans). See what an SBA microloan is for how the program works.
Local lender vs online lender: which is better for a small business?
Neither wins every time. Local banks and credit unions tend to be cheaper and slower, with stricter requirements; online lenders tend to be faster and more flexible, and they cost more for it.
| Factor | Local bank or credit union | Online lender |
|---|---|---|
| Borrowers who said costs ran higher than expected (Fed, 2025) | 37% at small banks, 32% at large banks | 60% |
| Why applicants chose it (Fed, 2025) | An existing relationship | Speed and the chance of being funded |
| What it usually reads | Tax returns, financial statements, collateral | Bank statements and credit |
| Products | Term loans, lines, SBA, real estate | Term loans, lines, advances, some factoring |
| Face-to-face help | Yes | Rarely |
The cost gap, in dollars: Say a credit union quotes 9% on a $75,000, five-year loan, and an online lender quotes 18% for the same term. The payments are about $1,557 and $1,905 a month, and total interest is about $18,413 versus $39,270. That roughly $20,900 difference is the price of speed, so pay it only when speed is worth it.
When to choose local, and when to look online
- Go local if you have two or more years of tax returns showing a profit, you can wait several weeks, and you want the lowest rate or an SBA loan.
- Go local, to a CDFI or microlender, if you are new, need $50,000 or less, or were turned down by a bank and want advice along with the loan.
- Look online if a time-sensitive opportunity cannot wait, your deposits are strong but your history is short, or your bank does not offer the product you need.
- Look at a specialist for factoring or equipment, where the lender's knowledge of the invoices or the asset matters more than its address.
Applicants with medium or high credit risk were much more likely than low-risk applicants to apply at online lenders, according to the Fed. Our comparison of a loan broker versus going straight to a bank covers the middle route.
How to vet a small business lender before you apply
Proximity does not prove legitimacy, and a website without a branch does not prove fraud. Check every lender the same way.
- Banks: confirm FDIC insurance in FDIC BankFind, which you can search by name, location or web address.
- Credit unions: look the institution up in NCUA's credit union locator and research tool.
- Non-bank lenders and brokers: lenders must register where they do business, and you can confirm registration with your state attorney general or banking regulator, according to the FTC (FTC).
- CDFIs: confirm the name appears on the CDFI Fund's certified list.
- Walk away from upfront fees. The FTC warns that legitimate lenders do not promise a loan before you apply, and that a fee demanded before the loan is granted, called insurance, processing or paperwork, is a red flag.
- Ask for the total cost in dollars, the payment schedule, every fee, prepayment terms, and whether the lender runs a soft or hard credit pull.
- Check who is calling. Someone claiming to be from SBA should be verified through SBA's own contact information before you share anything.
Our checklist of questions to ask a business lender and our guide on how to tell if a funding company is legit go further.
Small business funding near me when the local bank says no
A bank decline is common and often fixable. In the Fed survey, the reason denied applicants cited most often was that lender requirements were too strict (46%), which says more about the fit than about the business.
- Ask the bank for its reasons. Regulation B gives business applicants a right to the reasons for a denial, though you may need to ask in writing.
- Take the reasons to an SBDC advisor, who can tell you whether the fix is time, paperwork or a different product.
- Ask the same bank about an SBA-guaranteed loan. The guaranty exists for borrowers a lender sees as too risky without it.
- Try a CDFI, credit union or microlender with the same file.
- Then compare online options, using the full cost in dollars against what waiting would cost you.
If you are still deciding what kind of money to look for, our overview of small business funding sources lays out every option by stage, and how to apply for small business funding covers the documents each lender will want.
Where Quordx fits if you want a lender near you
Quordx is not a local lender, and not a lender at all. It is an online broker: you complete a roughly 10-minute application online, Quordx sends it to the panel lenders whose criteria fit, and those lenders make the call. That helps when your bank has said no to a product it does not offer, such as invoice factoring, larger equipment deals or working capital on a short history, and the business brings in about $17,000 or more a month.
If you need a small SBA loan, a microloan or a startup loan, a local CDFI, microlender or SBA Lender Match will serve you better. Quordx is not available to businesses in Virginia, Connecticut, Missouri or North Dakota, and anyone applying from California is shown a notice before starting.
Questions Business Owners Ask Before Applying
Are local banks better for small business loans than online lenders?
Often on cost, not always on access. In the Fed's 2025 survey, small-bank applicants were the most likely to be fully approved, and bank borrowers were far less likely than online borrowers to say costs ran higher than expected. Online lenders tend to be faster and more flexible on history, which is why owners who need speed or have short records use them.
Can I get a business loan from a credit union if I am not a member?
Usually you need to join first. Credit union members share a common bond, such as an employer, a group or where they live, so check whether you qualify for membership, then ask about business accounts and loans.
How do I find a CDFI near me?
Use the CDFI Fund's list of certified CDFIs, which you can sort by location and type, or search its award database by state. If nothing is close, check neighboring areas, since some CDFIs serve an entire state.
Does the SBA have an office near me that lends money?
SBA district offices offer training and local guidance but do not make 7(a), 504 or microloans; private lenders, Certified Development Companies and nonprofit intermediaries do. Use Lender Match to find SBA lenders, and SBA's microlender list for loans up to $50,000.
Can an SBDC help me get a business loan?
An SBDC does not lend, but its advisors offer no-cost consulting that can strengthen your plan, projections and loan request before a lender sees them.
Is it safe to use a lender with no local branch?
It can be, if you check it first. Confirm a bank in FDIC BankFind, confirm a non-bank lender's registration with your state regulator, and walk away from anyone who guarantees approval before you apply or wants a fee before the loan is granted.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources

Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures