

Small business funding the same day: what it really takes
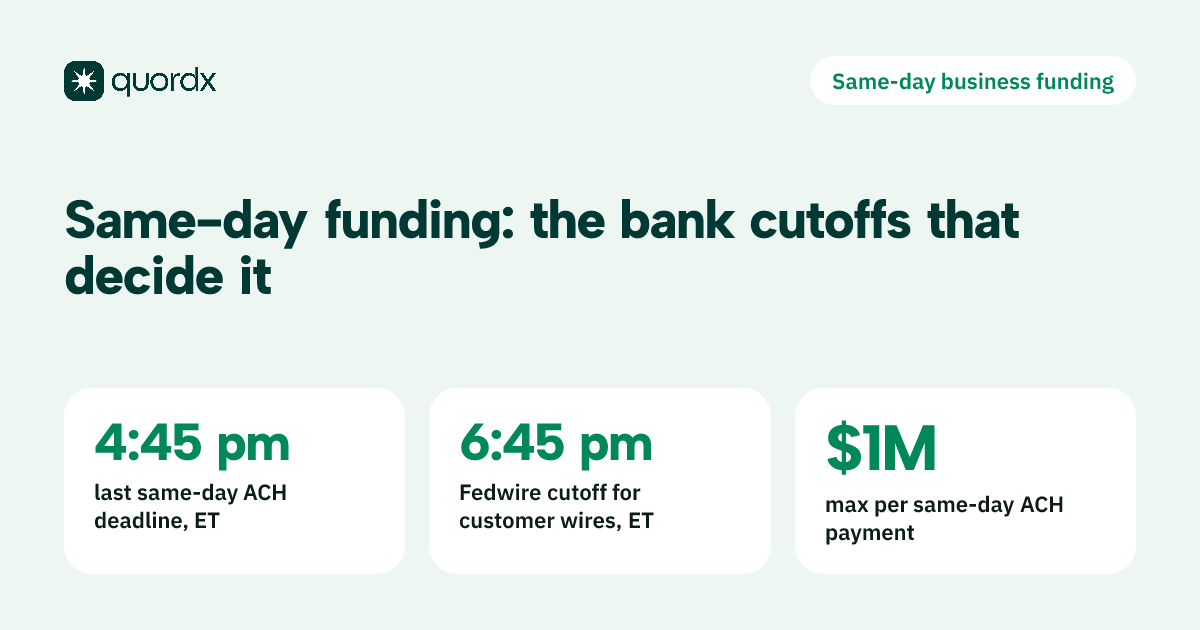
Same-day small business funding is possible, but only when a lender approves you, you e-sign, your bank account is verified, and the lender's bank sends the money before the payment system's afternoon cutoff. The last same-day ACH deadline for banks is 4:45 p.m. Eastern and the Fedwire deadline for customer wires is 6:45 p.m. Eastern; miss them and the money moves the next business day. Whether a lender sends money today at all is the lender's call, not the website's.
The short version: If you need money today, the realistic sources are a line of credit you already have, an offer waiting in your payment platform's dashboard, or a cash-flow lender that approves you before lunch. Have bank statements, ID and your business bank details ready, sign the moment the offer arrives, and ask whether the lender sends by ACH or wire. Expect to pay more for the speed.
Part of our guide to Business Loans.
Last updated · Reviewed by Cody Dreis
50+ Lenders|Funding in as little as 24 hours
What has to happen before money lands the same day
Five things have to finish in order, and each one has its own clock. A same-day promise only holds if all five fit before the cutoff.
- A credit decision. The fastest lenders decide from connected bank data and a few months of statements, so a complete file is the biggest thing you control.
- Your signature. Federal law says a contract can't be denied legal effect just because it was signed electronically, which is why same-day lenders use e-signature. If you have a co-owner who must also sign, their timing is now your timing.
- A verified bank account. The lender confirms the account belongs to the business that signed. A personal account, a name that doesn't match the entity or a newly opened account can each stop the transfer for a manual check.
- The transfer. The lender tells its bank to send an ACH payment or a wire. That has to happen before the bank's cutoff, which is earlier than the payment system's.
- Your bank posting it. Even after money settles, your bank decides exactly when it shows as available, within the limits in the next section.
Same-day ACH and wire cutoffs, from the Fed and Nacha
Most business funding moves by ACH. Same Day ACH runs in three windows on business days, according to the Federal Reserve's FedACH guidance, and Nacha's rules set when your bank must make the money available.
| If the lender's bank submits by (ET) | It settles at (ET) | Your bank must make it available by |
|---|---|---|
| 10:30 a.m. | 1:00 p.m. | 1:30 p.m., your bank's local time |
| 2:45 p.m. | 5:00 p.m. | 5:00 p.m., your bank's local time |
| 4:45 p.m. | 6:00 p.m. | End of your bank's processing day |
| After 4:45 p.m. | Next business day | 9:00 a.m. local time on that day |
Those are the bank deadlines, not the lender's: The times above are when the lender's bank must deliver files to the ACH operator. The lender and its bank set their own earlier cutoffs, so an approval at 4:30 p.m. Eastern rarely makes the last window.
Same Day ACH has a size limit: No single same-day payment can exceed $1 million, per FedACH. Nacha's members approved raising it to $10 million, effective September 17, 2027. Next-day credits must be available by 9:00 a.m. local time under a rule that took effect September 18, 2026; Nacha's earlier funds availability rule set the 1:30 and 5:00 p.m. deadlines.
Wires: later cutoff, weekdays only
A Fedwire transfer is immediate, final and irrevocable once processed, and the Fed's deadline for wires sent for a bank's customers is 6:45 p.m. Eastern. Fedwire runs Monday through Friday, excluding holidays. The Fed has announced plans to add Sundays and weekday holidays, but no earlier than 2028. A Friday approval after the cutoffs means Monday money.
The Fed's instant payment service, FedNow, runs around the clock, but it only helps when both the lender's bank and yours can use it. Ask your lender which rails it actually sends on.
Estimate your funding
Answer a few questions about your business to see a likely range.
Which funding can arrive the same day
| Funding type | Same day realistic? | What makes it fast | What slows it |
|---|---|---|---|
| Draw on a line of credit you already have | Often | Underwriting is already done | The lender's draw cutoff time |
| Offer in your payment platform's dashboard | Sometimes | Pre-underwritten from your sales data | The provider sets the timing |
| Sales-based advance or short-term working capital loan | Sometimes | Decisions from bank data | Late approval, account checks, paying off an existing advance |
| Invoice factoring, existing account | Sometimes | Customers already approved | Verifying each new invoice |
| Invoice factoring, new account | Rarely | Little until the account is set up | Setting up the account and checking your customers |
| Equipment financing | Rarely, and it goes to the vendor | Asset-backed decision | Vendor invoice, title and delivery |
| Bank term loan or SBA loan | No | Lower cost, not speed | Full underwriting; SBA's own review of a standard 7(a) runs 5 to 10 business days |
Notice the pattern: The products that can fund today are the ones where the slow work happened earlier: a line you opened months ago, a platform that has watched your sales, a factor that already knows your customers. For the next tier of speed, see the 48-hour business loan guide, and if the deadline is payroll, read how to cover payroll with a loan first, because missed payroll taxes carry their own penalties.
What same-day money costs: a worked example
Say a wholesale distributor needs $25,000 today because a supplier won't release a shipment until it's paid. Both offers below use made-up pricing to show the math. Neither is a quote or a market rate.
| Same-day advance (example) | Draw on an existing line (example) | |
|---|---|---|
| Pricing assumed | 1.30 factor rate | 18% APR |
| Repaid over | 6 months, 126 daily debits | 6 monthly payments |
| Payment | About $258 a day | $4,388.13 a month |
| Total cost | $7,500 | $1,328.78 |
| Rough annual rate | About 109% | 18% |
Speed bought at the deadline cost $6,171 more: in this example. The line was just as fast, because it was opened months earlier when nothing was on fire.
Decision rule: if you're borrowing for an emergency today, take the smallest amount that clears the deadline and compare offers in total dollars. Then open a line of credit while the business is healthy, so the next emergency is a draw instead of an advance. Our guide to business lines of credit explains how they work.
Why the lender decides when you get funded
A lender's ad describes its best case. Your file decides your case. Identity checks, fraud reviews, a request for one more statement or a mismatch between your application and your bank data can each push funding past the cutoff, and the lender doesn't owe you a same-day transfer just because the ad said possible.
Before you sign, ask four things in writing:
- What is your funding cutoff today, and do I have to sign before it?
- Do you send by ACH, same-day ACH or wire, and is there a fee for the faster one?
- Will anything be paid off first, such as an existing advance, and does that delay my money?
- What could stop the transfer after I sign?
For realistic timelines across every product, read how fast you can get a business loan.
Red flags in same-day funding offers
Urgency is what scammers sell to. The FTC's warning signs for advance-fee loans fit same-day offers closely: a promise of money regardless of your history, and a fee due before the loan arrives, whatever it's called. A legitimate lender's costs show up on your agreement, not as a payment you send first to "expedite" funding.
Also walk away from: pressure to sign before you've read the payment terms, requests for your online banking password instead of a secure bank connection, and anyone who says the money is guaranteed today before a lender has seen your statements. Our checklist on whether online business lenders are legit covers how to verify one.
Is Quordx a same-day funding option?
Usually not, and it's better to know that before you apply. Quordx is a broker, not a lender: it sends one application of about 10 minutes to several lenders, and each lender then runs its own review. Those lenders typically decide within 24 to 48 hours and fund in 3 to 7 business days after that, and every timing call is theirs.
If the money has to move today, your existing line, your processor's dashboard or your own bank is the faster call. Quordx is more useful for what comes next: lining up a line of credit or term loan before the next gap, with offers you can compare side by side. Lenders pay Quordx when a deal funds. Quordx does not serve Virginia, Connecticut, Missouri or North Dakota, and California applicants see a notice first.
Questions Business Owners Ask Before Applying
Can I get a business loan the same day?
Sometimes, mainly from cash-flow lenders, platform offers and lines of credit you already have. It needs an early approval, a quick e-signature, a verified account and a transfer before the afternoon cutoffs. A bank or SBA loan won't fund the same day.
What time do I need to be approved to get funded today?
There's no single answer, because each lender sets its own cutoff ahead of the payment system's. The last same-day ACH deadline for banks is 4:45 p.m. Eastern and the Fedwire deadline for customer wires is 6:45 p.m. Eastern, so an approval in the morning gives you the best chance.
Is a wire faster than ACH for business funding?
A wire has a later cutoff and is final once the Fed processes it, so it can land later in the day than same-day ACH. Some lenders may charge a fee for a wire or send only by ACH. Ask which one your lender uses before you count on today.
Can I get business funding on a weekend?
Usually not. ACH and Fedwire settle on business days, so a Friday approval after the cutoffs typically lands Monday. FedNow runs every day, but only if both banks use it and the lender sends that way.
The lender says it sent the money. Why isn't it in my account?
It may be in a later window or a next-day batch. For same-day ACH, your bank has until 1:30 p.m. or 5:00 p.m. its local time, or the end of its processing day, depending on the window. Ask the lender for the send time and method, then ask your bank.
Apply for Funding
No obligation · Initial inquiry doesn't impact credit · Takes about 10 minutes
Sources

Written by
Cody Dreis
Founder, Quordx Capital
Read full bio
Related articles
Keep exploring business loans
Quordx Capital is a business funding broker, not a lender. Lenders make every credit decision and set the rate, fees and terms, and not every business qualifies. Quordx may be paid by a lender when a deal funds. Full disclosures